How to Pay for Storm and Water Damage Repairs in the Texas Hill Country
A burst pipe or a Hill Country storm can leave you facing a deductible or damage your policy won't pay for. Here's how homeowners keep repairs moving, from insurance to financing.
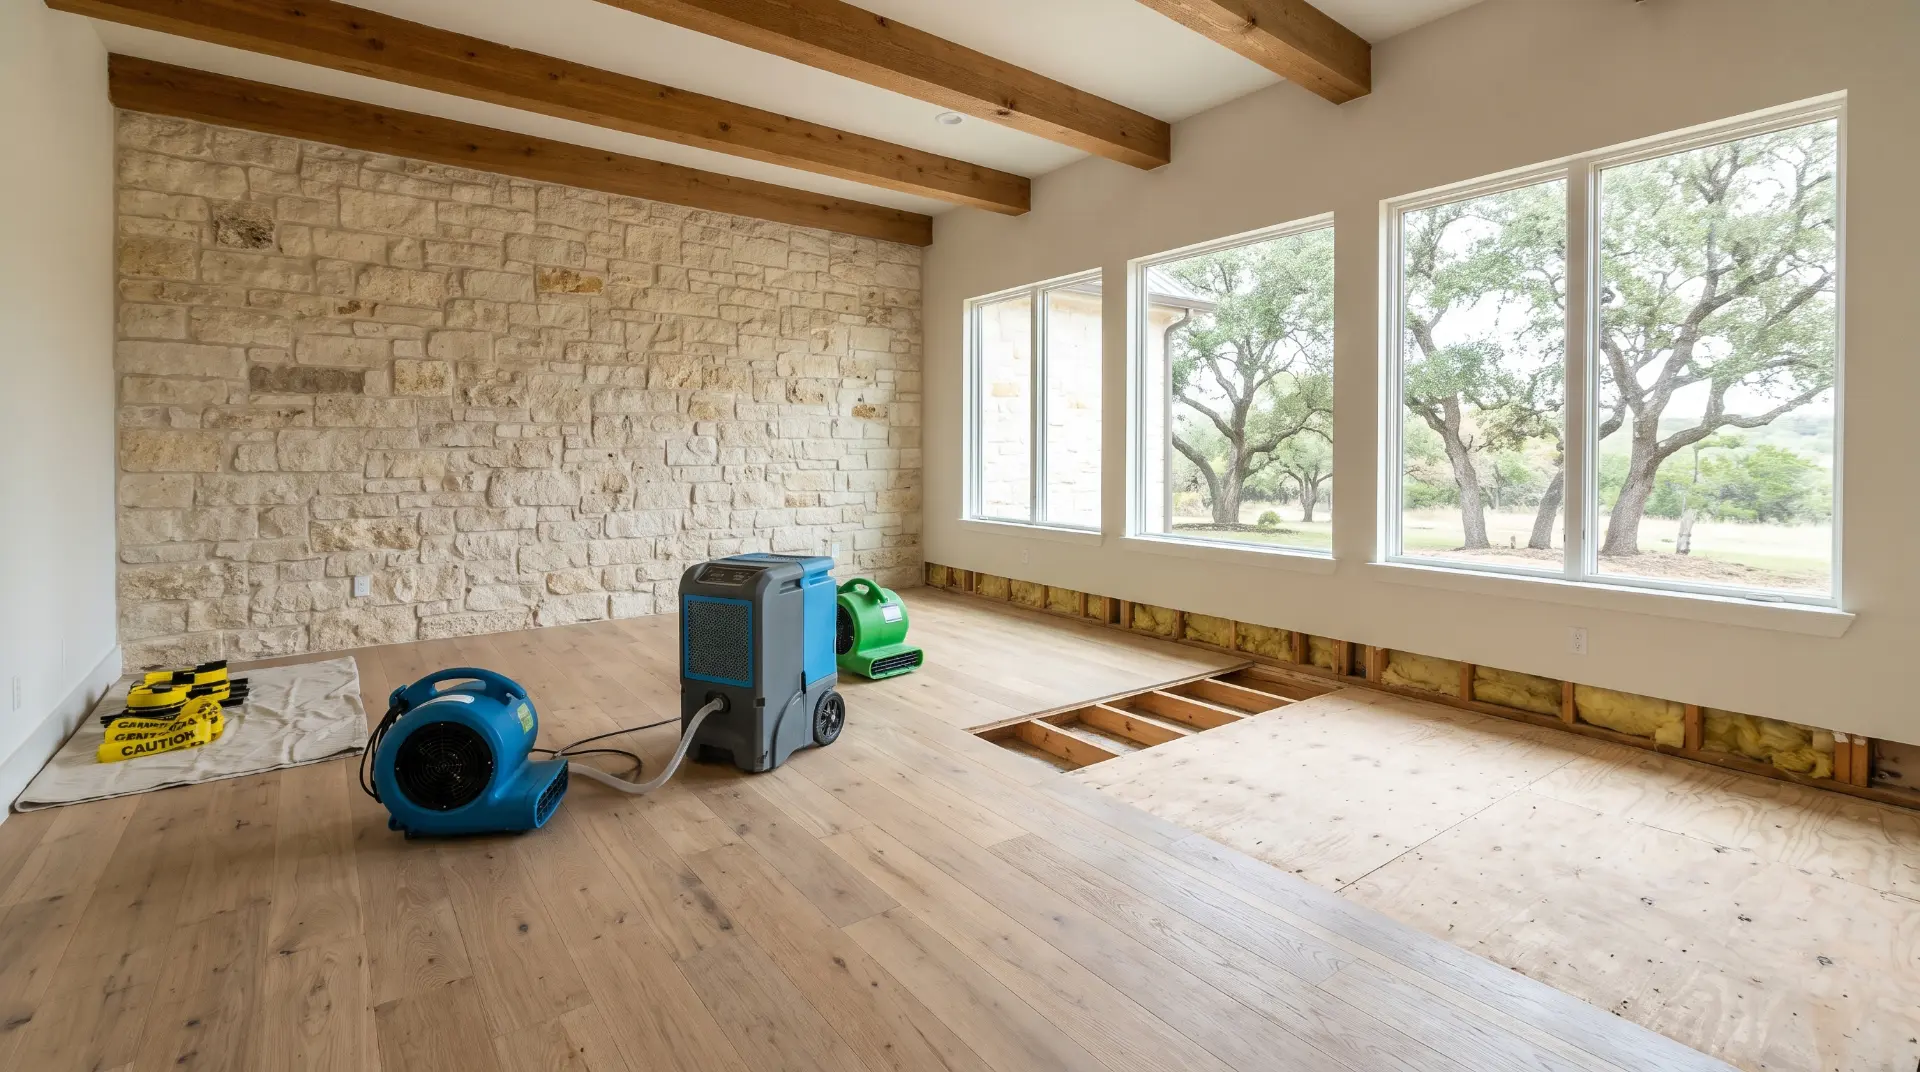
When a storm rolls through the Hill Country or a pipe lets go in the middle of the night, the first question is how fast you can get someone out to help. The second question comes right behind it: how am I going to pay for this?
This guide walks through why speed matters, what insurance typically does and doesn't cover, where homeowners usually find the money for repairs, and what to do in the first 48 hours.
Why Speed Matters After Water Damage
Water doesn't stay where it lands. It wicks up drywall, soaks into insulation, swells cabinet bases, and works its way under flooring. The longer materials stay wet, the more of them have to be removed and replaced.
There's also mold to think about. The EPA advises drying water-damaged materials within 24 to 48 hours to help prevent mold growth. Once mold takes hold, a repair project can turn into a remediation project, which adds time and cost.
That's why delays matter. Waiting a few weeks to figure out how to pay for repairs can make the final bill bigger.
What Homeowners Insurance Typically Does and Doesn't Cover
Every policy is different, so your own policy and your insurance agent are the final word. In general terms, here's how coverage often works:
- Sudden and accidental damage is often covered. Think of a burst supply line or a roof damaged by wind or hail that lets rain in.
- Gradual damage usually isn't. Slow leaks, long-term seepage, and wear and tear are commonly excluded.
- Flooding from rising water is not covered by standard homeowners insurance. Flood coverage is a separate policy, available through the National Flood Insurance Program or private insurers, and flood policies generally have a waiting period before they take effect.
Read your policy, and call your agent or insurance company with any questions about what applies to your situation. 40 Acres Construction doesn't handle or negotiate insurance claims; that conversation is between you and your insurer. What we can provide is a detailed written repair estimate and photos you can share with your insurance company.
The Gap: Deductibles and Uncovered Damage
Even when a loss is covered, you pay your deductible before insurance pays anything. Some Texas policies also have a separate wind and hail deductible calculated as a percentage of your home's dwelling coverage, which can be larger than homeowners expect.
Then there's everything outside the claim: damage your policy excludes, flood damage without a flood policy, or upgrades you decide to make while the walls are already open. These costs land on the homeowner, and they often arrive right when the household budget is already stretched.
Common Ways Homeowners Pay for Repairs
Most homeowners use one or a combination of these:
- Insurance proceeds for the covered portion of the loss.
- Savings or an emergency fund for the deductible and smaller uncovered items.
- Financing, such as a personal loan or personal line of credit, to cover the deductible or uncovered repairs without draining savings.
- Home equity, through a home equity loan or HELOC. This can work for planned projects, but Texas home equity rules include a required waiting period before closing, so it's usually not the fastest option after an emergency. We compare these options in Personal Loan vs. HELOC vs. Cash.
How Financing Works With 40 Acres Construction
Financing is available on every 40 Acres Construction estimate through our partner, Acorn Finance. Here's how it works:
- Check your options with no impact to your credit score. Pre-qualifying uses a soft credit pull, and you'll see personalized offers from multiple lenders.
- Compare and choose. Pick the offer that fits your budget, then apply for final approval directly with that lender.
- Get funded fast. If approved, you could receive funds as soon as the next business day and use them to pay for your repairs.
In Texas, loan amounts range from $2,000 to $100,000. You're never required to use financing; it's simply another way to keep your repairs moving. Learn more on our financing page.
The First 48 Hours Matter Most
The first two days after water damage are when you protect your home and your options: get everyone safe, stop the water if you can, photograph everything before it's moved, report the loss to your insurance company, and get drying started. We walk through each step in detail in What to Do in the First 48 Hours After Water Damage.
One step worth repeating here, because it affects what you'll pay out of pocket: keep every receipt, including hotel stays, emergency supplies, and anything you buy to protect your home.
If Mold Has Already Started
If you see or smell mold, Texas law requires mold assessment and mold remediation to be performed by separate, independent licensed companies. An independent licensed assessor evaluates the problem and writes the remediation protocol; a licensed remediation contractor carries it out. 40 Acres Construction is a Texas-licensed mold remediation contractor (License #MRC2230). Learn more about our mold remediation services.
We're Here to Help You Rebuild
40 Acres Construction is a veteran-owned general contractor based in Boerne, serving homeowners across Kendall County, Kerr County, Comal County, Bandera County, and northern Bexar County. If you're dealing with storm or water damage, visit our water damage restoration page or call us at (830) 400-4420.
40 Acres Construction is not a lender and does not make credit decisions. Financing is offered through Acorn Finance's lending partners and is subject to credit review and approval. This article is general information and is not insurance or legal advice; review your policy and contact your insurance company with coverage questions.